11 November 2026 | Wednesday | News
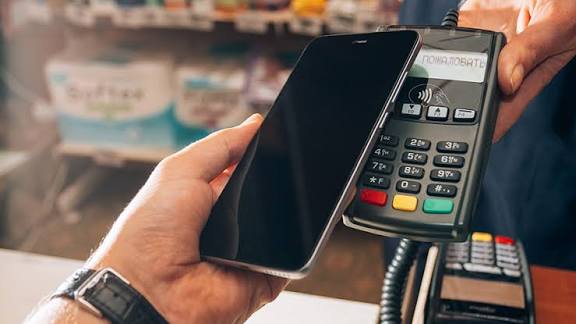
Image Source: Public Domain
Oman recorded a 99.4% increase in mobile payment transaction volumes, while ATM transactions declined by 14.5%, as consumers and businesses increasingly turned to electronic payment methods.
According to the latest payment system figures, the total value of ATM transactions stood at RO2.66 billion, reflecting lower activity in cash withdrawals.
In contrast, transactions processed through the Mobile Payments Clearing and Switching System (MPCSS) recorded a 99.4% increase in volume, while their total value rose by 87.9%.
The figures indicate growing use of mobile and instant payment services as Oman continues to expand its digital payment infrastructure.
Point-of-sale (POS) transactions increased by 47.4%, reaching a total value of RO4.23 billion.
The rise reflects greater use of payment cards and electronic payment terminals for everyday purchases, supported by wider acceptance of digital payment methods.
E-commerce transactions also increased by 20.4% to RO1 billion, indicating continued growth in online shopping and digital retail payments.
The figures show that electronic transactions are gaining ground across both physical stores and online platforms, while cash withdrawal activity has declined.
A significant development in Oman's payment sector was the introduction of Maal, the country's domestic payment card, in 2025.
The initiative is intended to strengthen national control over payment processing, reduce transaction costs and improve the security of payment data.
By developing its own domestic card infrastructure, Oman aims to reduce reliance on external payment networks for local transactions.
The Maal card forms part of wider efforts to establish a more efficient national payments network and support the increasing use of electronic financial services.
Omani banks have also expanded their participation in Afaq, the Gulf Cooperation Council's Real-Time Gross Settlement (RTGS) system.
The platform allows participating financial institutions to process cross-border payments within the GCC through a shared regional settlement network.
Its expansion is intended to improve transaction efficiency, reduce settlement costs and strengthen financial connections between Gulf countries.
For banks and businesses operating across the region, Afaq provides an additional channel for transferring funds through participating financial institutions.
The development supports efforts to improve regional payment infrastructure as trade and financial transactions between GCC economies continue to grow.
Oman has also implemented the second phase of its International Bank Account Number (IBAN) system for domestic bank transfers.
The expansion is designed to improve the accuracy of payment instructions and reduce errors associated with bank account identification.
Using standardised account numbers can help financial institutions process transfers more reliably while improving compatibility with international banking practices.
The measure forms part of the country's broader programme to modernise financial infrastructure and improve the efficiency of domestic payments.
The continued development of OmanNet, MPCSS and the Automated Clearing House (ACH) is supporting the growth of electronic payments across the country.
These systems provide infrastructure for processing card transactions, mobile payments and bank transfers, helping financial institutions manage increasing transaction volumes.
The latest figures suggest that consumers and businesses are making greater use of digital payment channels, particularly for retail purchases, mobile transfers and online transactions.
While cash remains part of Oman's payments market, the decline in ATM activity alongside growth in electronic transactions points to changing payment preferences.
For banks and payment service providers, the shift creates opportunities to expand mobile banking, instant transfers and merchant payment services.
The continued adoption of these services will depend on reliable payment infrastructure, transaction security and wider acceptance among consumers and businesses.


Fintech Business Asia, a business of FinTech Business Review
© 2026 FinTech Business Review. All Rights Reserved.